There is a strategy that appears simple in outline and catches out a great many investors in execution. Buy a property below market, renovate it, place a tenant, refinance into long-term financing based on the improved value, and use the released capital for the next acquisition. Repeat.
The logic is sound and the mechanics are where it goes wrong. The refinance step depends on an appraisal, on rental income, on lender requirements about how long the property must be held, and on the property qualifying under underwriting criteria that the investor may not have examined before starting.
Anyone planning this route should understand how investment loans for rental properties are assessed at the refinance stage before committing to the acquisition, because the entire strategy depends on that step working roughly as modelled.
Why the Refinance Is the Whole Strategy
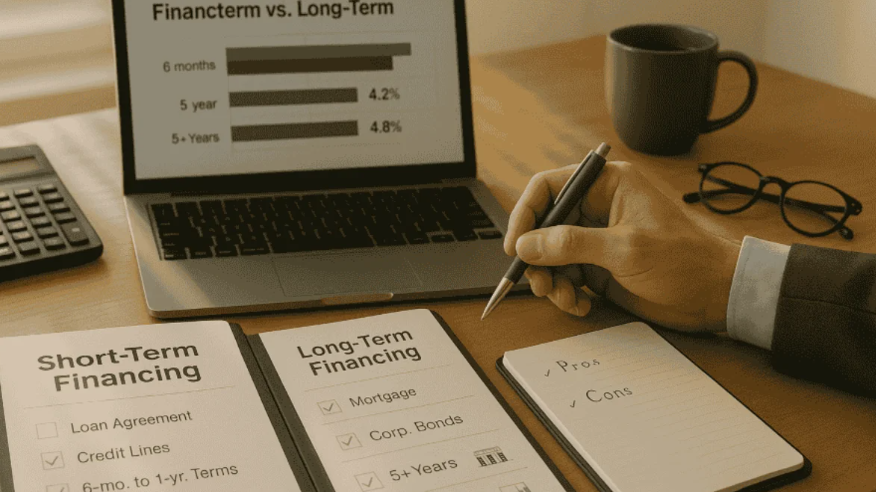
The short-term financing that funds acquisition and renovation is expensive by design. It is priced for a period measured in months.
Holding a property on that financing indefinitely destroys the return, since the carrying cost exceeds what a rental produces.
The refinance therefore is not an optional optimization. It is the event that converts an expensive project loan into a sustainable long-term position, and until it completes the investor is exposed to a cost structure the property cannot support.
That makes the refinance the step to plan first and the one to verify is achievable before the acquisition closes.
What the New Lender Will Assess
Long-term rental financing is generally underwritten on the property’s income rather than on the borrower’s personal earnings, which is what makes it accessible to investors building portfolios.
Rental income is established from a signed lease, or from a market assessment where the property is not yet tenanted. A property with a tenant in place at a documented rent is substantially easier to underwrite than a projection.
Coverage is the central calculation: rental income against the total monthly obligation including principal, interest, taxes, and insurance. Lenders look for a margin above break-even, and the required ratio affects both approval and pricing.
Appraised value determines how much can be borrowed, and it is the variable the investor controls least. An appraisal below the projection reduces the amount released and can leave capital trapped in the property.
Property condition affects both the appraisal and the lender’s willingness, which is why the renovation needs to be genuinely complete rather than substantially complete.
Credit history and reserves still matter even where personal income documentation is minimal.
The Seasoning Question
The requirement that catches out the most investors is seasoning, meaning how long a property must be owned before a lender will base financing on its current appraised value rather than on the purchase price.
Requirements vary between lenders and between loan products, and they are frequently measured in months.
Where a seasoning requirement applies and has not been met, the lender may limit lending to a percentage of the original purchase price plus documented improvements, which for a property bought well below market means considerably less capital released than the investor expected.
This is a question to ask before purchasing rather than at the refinance application. The answer determines the timeline and, in some cases, which lender the strategy depends on.
Documentation of improvement costs matters where lending is based on purchase price plus improvements, which is one more reason to keep proper records of renovation spending.
Where the Numbers Come Up Short
Several outcomes leave an investor with capital still tied up in the property.
The appraisal comes in below expectation, which is the most common. Appraisals are independent assessments and optimistic projections do not influence them.
The rent achieved is lower than modelled, reducing the coverage ratio and therefore the supportable loan amount.
Renovation costs exceeded budget, so more capital went in than the refinance releases.
The lender’s maximum lending percentage is lower than assumed, which is a matter of checking terms rather than of the property.
Interest rates moved, changing the payment and therefore the coverage calculation.
In each case the position is not necessarily bad. The investor owns an improved, tenanted property. What has not happened is the capital recycling that funds the next acquisition, which means the strategy slows rather than fails.
Planning the Transition Properly
A few practices make this step considerably more reliable.
Confirm refinance criteria before acquiring. Speak to the lender who will provide the long-term financing and understand their requirements around seasoning, coverage, condition, and documentation.
Model conservatively on value and rent, and check whether the project still works if the appraisal comes in somewhat below your estimate.
Ensure the short-term loan term accommodates the seasoning period plus the refinance process, or that extension terms are known and affordable.
Place a tenant before applying where possible, since a documented lease strengthens the file considerably.
Complete the work properly, since a property with outstanding items appraises lower and may fail condition requirements.
Keep renovation documentation, including invoices and permits, which supports both the appraisal and any cost-based lending calculation.
Hold reserves beyond the project, because a refinance that releases less than planned is a manageable situation for an investor with liquidity and a serious one for an investor without.
Being Realistic About the Pace
The version of this strategy described online generally assumes every step works perfectly and the cycle repeats quickly.
In practice appraisals disappoint, seasoning takes time, tenants take time to place, and some proportion of capital stays in each property rather than being fully recycled.
That is not a reason to avoid the approach, which remains one of the more effective ways to build a rental portfolio without unlimited capital. It is a reason to model it with realistic assumptions, verify the refinance path before the acquisition, and treat a slower cycle as the expected case rather than the disappointing one.